Crorebet Withdrawal: IMPS Payouts Step by Step
Crorebet withdrawals leave by IMPS to a bank account only, with ₹500 the minimum shown in the app and maximum cashout tiers starting at ₹50,000. Verification must be complete first. Our three August 2026 test payouts landed in 22 minutes, 41 minutes and 2 hours 10 minutes.
Set the payout side up first
₹500 minimum · IMPS to bank · fastest documented settlement 22 minutes.
Open the App- 18+ only
- Anjouan licensed
- IMPS payouts
- ₹500 minimum
- Three payouts documented
- IMPS
- Bank transfer
- UPI in
- PAN KYC
Crorebet withdrawal facts at a glance
Six numbers decide whether a payout system is workable: the rail, the floor, the ceiling, the speed, the cost and the gate you have to clear first. Each figure below was read off the app or measured on a real transfer in August 2026.
| Property | Value |
|---|---|
| Payout rail | IMPS bank transfer — the only option offered |
| Minimum request | ₹500 shown in the app |
| Maximum per cashout | Tiered, starting at ₹50,000 and rising with account standing |
| Fee charged by the cashier | None observed on three test payouts |
| Fastest settlement measured | 22 minutes (₹500, 14 August 2026) |
| Slowest settlement measured | 2 h 10 min (₹7,000, 18 August 2026) |
| Verification required | Yes — before the first withdrawal, not before the first deposit |
| Wallet or UPI payout | Not available |
| Beneficiary name rule | Must match the verified account holder name exactly |
| Rail availability | 24×7, including weekends and bank holidays |
Last verified: 20 August 2026. Figures read from the version 3.6 Android build and cross-checked against bank credit entries for three payouts totalling ₹10,000.
On this page
Why are withdrawals IMPS-only when deposits accept UPI?
Because money flowing in and money flowing out are treated as different regulatory problems, and the platform has solved only the easier one. This is the clearest limitation of the payment stack here, and it is worth stating plainly rather than dressing up.
On the way in you get four routes, all of them instant and all of them one PIN entry away, as documented in the deposit methods and limits guide. On the way out you get a single rail that needs an account number, an IFSC code and a name that matches your identity documents. That is more friction than a UPI handle, and there is no toggle to change it.
Three practical consequences follow. Anyone without a bank account in their own name cannot be paid at all, so a shared or family account is not a workaround. Second, a payout can fail on a data-entry error that a UPI handle would have caught instantly. Third, the psychological effect is real: money that takes ten seconds to deposit and a form to withdraw tends to stay in the account, which is precisely why we suggest withdrawing on a schedule rather than when you happen to think of it.
We flag this as a limitation, not a red flag. Bank-only payouts are common across offshore operators serving India, and the licence position and payout evidence are examined separately in our trust investigation.
What is IMPS and why does the choice matter?
IMPS is India's round-the-clock interbank transfer service, and choosing it means your payout depends on two institutions rather than one. Knowing that changes how you read a delay.
Definition: IMPS
The Immediate Payment Service moves funds between Indian bank accounts using an account number and IFSC code, settling within minutes and operating every day of the year. Unlike a UPI handle, it addresses the account directly, so the receiving bank's own systems decide when the credit appears in your passbook.
That last point explains most confusion about payout speed. Once the operator releases a transfer, the money is in the network and the remaining wait belongs to your bank. Two customers can request the same amount at the same minute and see it credited fifteen minutes apart purely because one banks somewhere with a slower batch cycle.
It also means a wrong IFSC does not silently swallow money. The transfer is rejected and the amount returns to your gaming balance, usually within the hour. Annoying, recoverable, and a reason to check the code against your cheque book instead of typing it from memory.
How do you add bank details and request a payout?
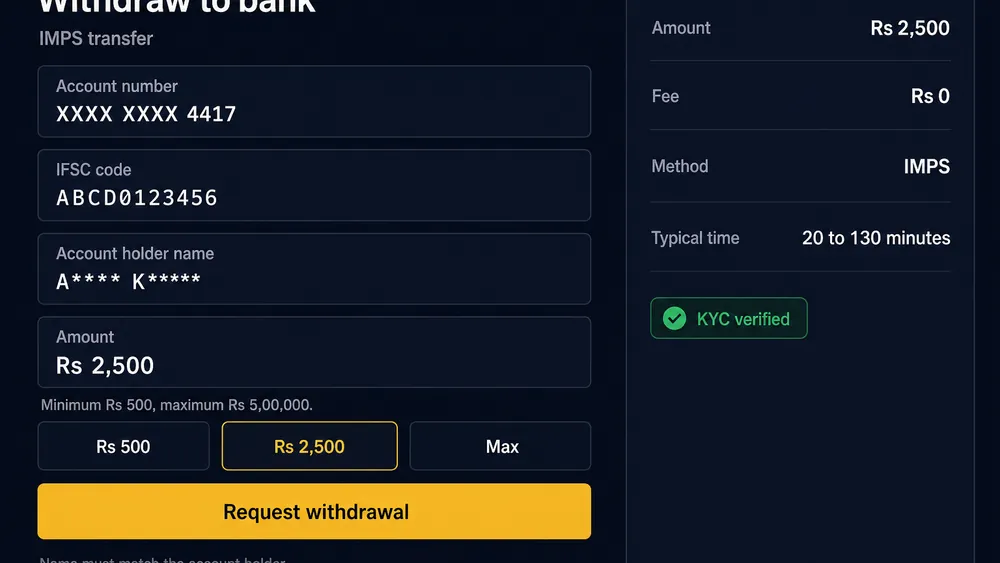
Six steps, and the first one is the one people skip. Verification has to be finished before anything else in this list will work, so start there even if you have no intention of withdrawing yet.
- Finish verification before you need it
Submit identity documents and wait for approval. Our PAN upload on 13 August 2026 went in at 9:12 pm and cleared 1 hour 5 minutes later, which was faster than we expected for an evening submission.
- Open the cashier and switch to withdrawal
Tap the wallet icon and move from the deposit tab to the withdrawal tab. Bank transfer is the only entry, so there is no method comparison to make.
- Add the beneficiary account
Enter the account number twice, then the IFSC of your own branch. Saved beneficiaries are reused, so this is a one-time job per bank account.
- Copy the name from your passbook
Type the account holder name exactly as the bank prints it, including initials and any middle name. Do not abbreviate and do not guess.
- Enter ₹500 or more
The field rejects smaller requests. Check that no bonus wagering is still open, because an unfinished promotion holds the whole balance rather than just the bonus portion.
- Submit and note the exact time
Record the timestamp so you can measure the wait rather than estimate it. That single detail turns a vague complaint into a traceable support ticket.
What if your bank is not recognised?
Check the IFSC rather than the bank name. IMPS addresses branches, so a small co-operative bank that participates in the network works fine while a valid-looking code with one transposed character does not. Cross-check the code on your cheque leaf or in your bank's app, and if a correct code is still rejected, that is a case for support escalation rather than repeated attempts.
Why must the account name match your bank record exactly?
Because payouts are matched against your verified identity, and any gap between the two names reads as a third-party transfer. Anti-money-laundering rules make operators refuse those, whatever the explanation.
We tested the boundary on 17 August 2026 by omitting a middle name that appears on the bank record. The request was accepted by the interface, then returned to the gaming balance 26 minutes later with a note about beneficiary details. No money was lost and nothing was frozen, but the payout had to be resubmitted from scratch — an avoidable hour for a two-word difference.
The rule extends further than spelling. A payout will not go to a spouse's account, a parent's account or a business account, even with proof of relationship, because the name on the receiving account has to be the name on the verified profile. If your bank record and your identity document disagree with each other, fix that at the bank first; the document requirements are set out on the sign-up and KYC page.
Take one screenshot now. Photograph the name line on your passbook or bank app and keep it in the same folder as your deposit receipts. Every payout query we have seen resolves faster when the account holder can produce that one image immediately.
When does the KYC gate apply?
On the way out, never on the way in. You can register, deposit and place stakes on an unverified account, and the verification check appears only when you first ask for money back — which is the worst possible moment to discover it.
That sequencing is deliberate across the category and it is not unique to this platform, but it does mean a new account is not really usable until documents are approved. Our own approval took just over an hour on a weekday evening, which is quick; the same queue on a busy Sunday during an live dealer fixture is a different proposition, and nobody can promise you an hour.
Two things shorten it. Submit a document where the name matches your bank account exactly, and photograph it flat with no glare, because rejected images are the main cause of a second round trip. Verification is a one-time cost with no downside, so treat it as part of setting the account up rather than as a step you reach later.
Verify before you have money on the line
One document · approved in 1 hour 5 minutes in our August 2026 test · unlocks the payout side permanently.
Verify Your AccountWhy is my withdrawal pending?
Six causes cover it, and the interface shows the same pending label for all of them, which is the actual usability problem. Work down this table in order, because the first two explain the large majority of held payouts.
| Symptom | Cause | Fix |
|---|---|---|
| Amount returns to balance within the hour | Beneficiary name does not match the verified name | Correct the name from your passbook to the character and resubmit |
| Request never leaves pending | Verification incomplete or a document was rejected | Re-upload a flat, glare-free image and wait for approval before requesting again |
| Whole balance locked, not just the bonus | Bonus wagering still open | Complete or forfeit the promotion; the terms are broken down on the bonus page |
| First payout slower than later ones | Manual review applied to a new account's first withdrawal | Wait; this is a one-off check rather than a fault, and later requests skip it |
| Payout rejected, money back in the wallet | Wrong IFSC, or an account number with a transposed digit | Re-enter both from a cheque leaf and delete the faulty saved beneficiary |
| Released by the operator but nothing in the bank | Receiving-bank outage or maintenance window | Check your bank's status, then wait; IMPS retries rather than dropping the transfer |
How long should you wait before contacting support?
Four hours for a normal request, or twenty-four if it is your first payout and manual review is plausible. Chasing earlier rarely speeds anything up, and our support test on 15 August 2026 answered in 3 minutes 40 seconds, so the queue is not the bottleneck when you do need it. Bring the request timestamp, the amount and the last four digits of the account.
How long did our test payouts take?
Twenty-two minutes for ₹500 on 14 August 2026, 41 minutes for ₹2,500 on 16 August, and 2 hours 10 minutes for ₹7,000 requested late at night on 18 August. Larger amounts and overnight submissions were slower, which is the pattern you would expect if a manual check sits in the middle.
Three transfers prove that money comes out; they do not prove an average. We keep the full log with submission timestamps, credit timestamps and bank names on the payout timing record, and we add to it rather than rewriting the summary here.
Do payouts run on weekends and holidays?
Yes, because the rail itself never closes — IMPS settles on Sundays, Diwali and 26 January alike. Where a weekend can cost you time is the operator's own review queue and the occasional maintenance window at a receiving bank, neither of which is governed by the network.
Our slowest documented payout was a Tuesday night request rather than a weekend one, so we have no evidence that Saturdays and Sundays are systematically worse here. The practical advice is unglamorous: request during Indian business hours if the amount matters to you, and do not submit your first ever payout an hour before you need the money.
What about TDS on winnings?
Winnings from real-money gaming attract tax deducted at source under Indian tax rules, and the obligation to declare that income sits with you. We are not going to calculate anybody's liability, and any site that offers to should be treated with suspicion.
What we can say is what matters procedurally. Keep your own record of deposits, withdrawals and net position, because an offshore operator's statement is not a substitute for your own accounting. The reporting position for players using platforms licensed outside India is not identical to that for domestic operators, and it has been moving — which is exactly why a qualified chartered accountant or tax adviser is the right person to ask about your circumstances rather than a gaming guide.
Nothing on this page is tax, legal or financial advice. The broader regulatory picture, including the contested national framework and the states that ban real-money gaming separately, is set out neutrally on our regulation overview. Check what applies where you live before you play.
Keep the payout side ready
₹500 minimum · IMPS 24×7 · no cashier fee on ₹10,000 of test payouts.
Request a Payout- IMPS
- Bank transfer
- PAN KYC
- 24×7 rail
Payout strengths and weak points
Pros
- All three test payouts arrived, the fastest in 22 minutes
- No cashier fee deducted on ₹10,000 of withdrawals
- IMPS settles every day of the year, including bank holidays
- A rejected transfer returned to the gaming balance within the hour
- Verification cleared in 1 hour 5 minutes on a weekday evening
Cons
- Bank transfer is the only rail — no UPI or wallet payout at all
- ₹500 minimum is five times the deposit floor
- The KYC gate appears on the first withdrawal rather than the first deposit
- Every hold shows the same pending label, with no reason given
- An exact-name requirement rules out paying into any other person's account
Verdict on Crorebet withdrawals
Judged on the only test that counts, the money came back — three times, in 22 minutes, 41 minutes and just over two hours, with nothing deducted. That is a better record than much of this category manages, and the round-the-clock rail means a Sunday request is not automatically a Monday problem. The cost is friction and opacity. One payout route means anyone without a bank account in their own name is excluded, the ₹500 floor is high relative to a ₹100 deposit, and a held request tells you nothing about why. Verify early, copy your bank name exactly, and withdraw on a schedule rather than in a hurry.
Ready to cash out?
Three documented payouts · ₹500 minimum · IMPS direct to your bank account.
Get the Crorebet App- 18+ only
- Anjouan licensed
- IMPS payouts
- No payout fee observed
- Hindi and English
Frequently asked questions
What is the minimum Crorebet withdrawal?
₹500 was the minimum shown on the withdrawal screen when we checked it on 20 August 2026. That is five times the deposit floor, so a ₹100 deposit cannot be taken straight back out — you need at least ₹500 of withdrawable balance before the request will submit.
Crorebet se paisa kaise nikale?
Pehle KYC pura karo, phir cashier mein withdrawal tab kholo aur bank transfer chuno. Account number, IFSC aur bank wala exact naam daalo, ₹500 ya usse zyada amount likho, aur submit karo. Paisa IMPS se seedha bank account mein aata hai.
Can I withdraw to PhonePe, Google Pay or Paytm?
No. Deposits accept all three, but payouts leave only by IMPS to a bank account, and no UPI handle or wallet option appeared on the withdrawal screen. This asymmetry is a genuine limitation of the platform rather than a setting you can change.
How long does a Crorebet withdrawal take?
Between 22 minutes and 2 hours 10 minutes across the three payouts we documented in August 2026, with the slowest being a ₹7,000 request submitted late at night. Three transfers are not a statistical sample, and your own bank's processing adds to whatever the operator takes.
Why is my withdrawal still pending?
The six causes we identified are a bank name that does not match your verified name, incomplete KYC, unmet bonus wagering, a first payout sitting in manual review, a wrong IFSC and a receiving-bank outage. Each shows the same pending label, so check them in that order.
Do I need KYC before my first withdrawal?
Yes, and this is where the account structure catches people out. Deposits work on an unverified account within minutes of signing up, but no payout is released until identity documents are approved. Verifying on day one removes a wait you would otherwise meet with money on the line.
Is tax deducted on winnings?
Winnings from real-money gaming attract tax deducted at source under Indian tax rules, and the responsibility to declare income sits with you rather than with an offshore operator. We do not calculate anyone's liability. Speak to a qualified tax professional about your own position.
Do withdrawals process on Sundays and holidays?
IMPS runs around the clock including weekends and bank holidays, so the rail itself never closes. What can slow down is the operator's own review queue and occasional maintenance windows at receiving banks, which is why a Sunday-night request may sit longer than a weekday one.